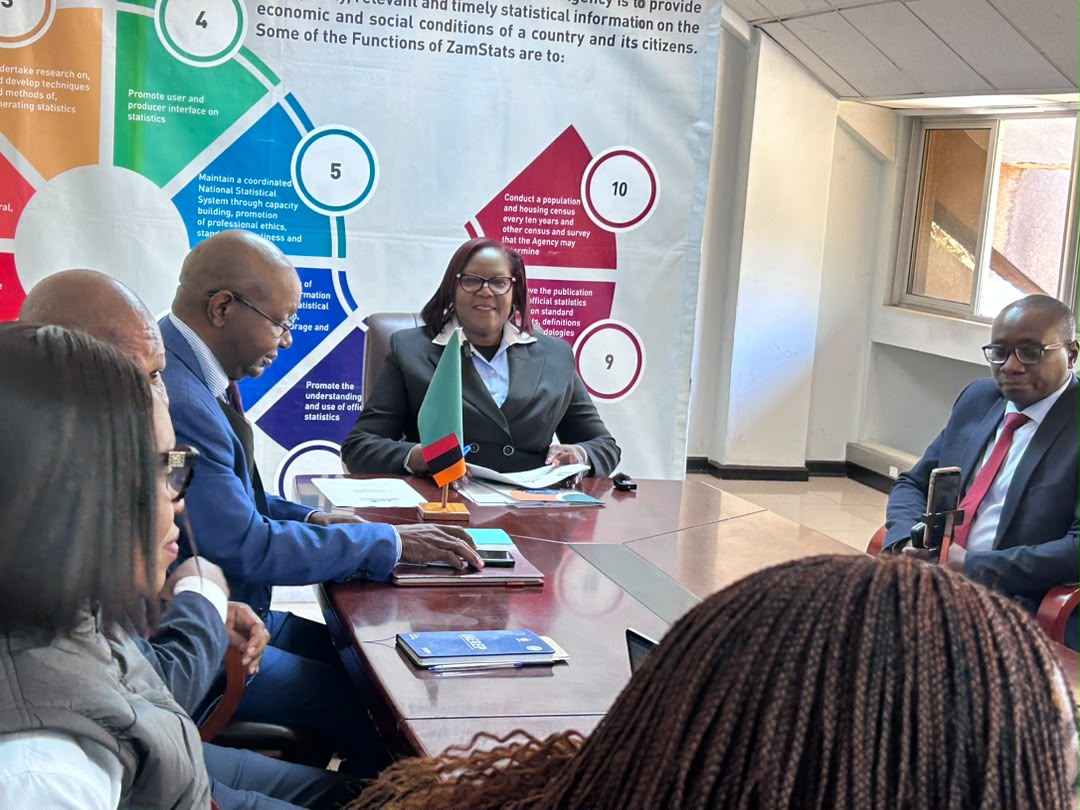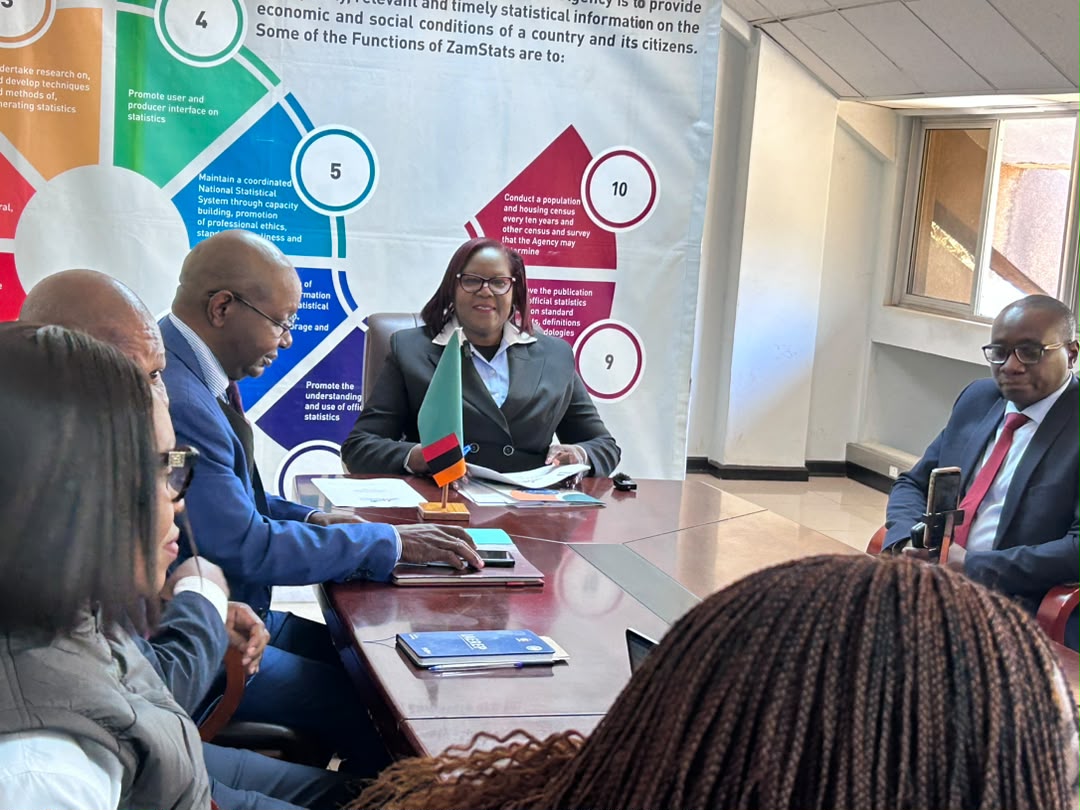
Samuel Sikazwe, ZamStats, LUSAKA | 30 JULY 2026— Zambia successfully anchored its annual inflation at 6.5% in July 2026, preserving the stability achieved in June. Alongside this domestic pricing baseline, the national year-to-June trade surplus reached K26.1 billion or $1.4 billion mark from January. Beneath these macroeconomic indicators, regional markets are demonstrating distinct economic trajectories. Lusaka Province registered an 8.7% annual rate, reflecting its dense commercial activity and Luapula Province recorded an impressive 3.9%, highlighting the diverse pricing environments operating within the broader economy.
A Steady Headline Hides a Moving Split Beneath It
The overall rate remained static as the components beneath it moved in opposite directions. Food inflation eased, and non-food inflation climbed, keeping the headline number frozen even as the underlying pressures changed shape entirely. This internal divergence means the cost-of-living shifts across the retail counter, prompting corporate planners to navigate a market where basic sustenance becomes cheaper as energy inputs adjust.
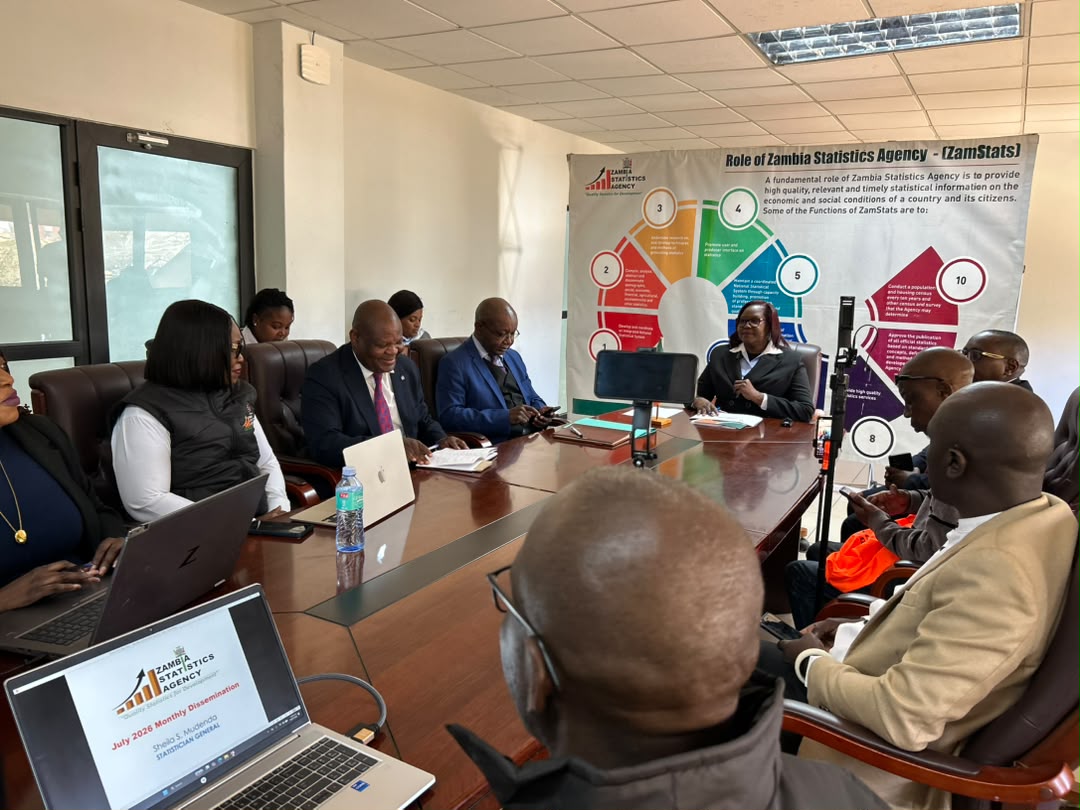
Ms. Sheila S. Mudenda, Statistician General of the Zambia Statistics Agency, presented the figures in the Agency's July 2026 Monthly Bulletin, suggesting the headline number requires closer reading.
July's data rewards that kind of scrutiny. Food inflation slowed to 6.4% in July, down from 6.7% in June, driven by softer prices for cereals, maize grain, and several household staples. Non-food inflation moved in the opposite direction, rising to 6.7% from 6.0% the previous month, pushed higher by furniture, paraffin, charcoal, and vehicle purchases. The monthly figure moved too, rising to 0.2% in July from 0.1% in June, offering an early signal of upcoming pricing trends. Inflation data remains one of the most important inputs into the Bank of Zambia's monetary policy framework. The key questions now worth pondering is: Will interest rate cuts become deeper as inflation moves closer to the lower end of the target band? Are we entering a period of increasing upside inflation risks as inflation approaches its trough? Or is there still room for inflation to decline further?
Ten Provinces, One Inflation Rate, Very Different Realities
Zambia's ten provinces do not experience inflation equally, and July's figures lay out precisely how unevenly the numbers fall. Lusaka Province accounted for the largest single contribution to the national rate, at 2.5 percentage points, followed by Copperbelt Province at 1.3 percentage points. Luapula and North-Western Provinces sit at the opposite end, each contributing only 0.2 percentage points to the national total. This figure barely registers against Lusaka's share, despite both provinces carrying equal weight in the calculation of the headline rate. As the national commercial hub, Lusaka absorbs higher urban demand and concentrated consumer spending, which pushes prices upward. Luapula operates with tighter, localized agricultural supply chains where proximity to domestic farming outputs keeps basic commodity prices highly competitive.
Eastern Province offers a rare point of stability in a report otherwise defined by movement, holding at 5.0% to sit at the midpoint between the two provincial extremes. Inflation declined in Luapula, Northern, and Southern Provinces over the same period, dropping consistently across rural agricultural belts. It increased in Central, Copperbelt, Lusaka, North-Western, and Western Provinces, tracking closely with zones of intense industrial and urban activity. This confirms that a national inflation rate naturally flattens the extremes of the ten local economies it represents. Distributors operating national supply chains must price their goods according to these provincial realities rather than relying on a single aggregate number.
Where The Numbers Meet the Shopping Basket
Zambia's Consumer Price Basket draws on 440 items and more than 23,000 price quotations collected across all 116 districts every month, built specifically to catch this regional divergence. Mealie meal sits at the centre of that basket. The national average price of a 25-kilogram bag of breakfast mealie meal fell by 7.53% on the month, from K272.66 to K252.13, indicating straightforward relief. The same data places the maximum price for that identical bag at K400 in Chilubi, against a minimum of K199 in Lusaka, a gap of more than double within a single reporting month. A national average of K252.13 describes neither of those two realities with any precision, proving that geographical isolation plays a key role in regional food markets.
Maize grain moved in a similar direction. The monthly price for a 20-litre tin fell by 9.90%, from K110.80 to K99.83, and the annual price fell by 12.32%. Not every commodity eased. Charcoal prices rose by 3.88% over the month, a modest but telling counterpoint in a household budget where fuel for cooking often competes directly with the cost of the meal itself. Diesel prices fell by 12.46% on the month, a decline with direct implications for Zambia's export logistics and domestic transport, which depend on road haulage. This double-digit drop in diesel offers a structural advantage to the commercial logistics sector, directly impacting the national trade balance. Because the Zambia Statistics Agency reports international trade data with a one-month lag, the July bulletin confirms a K4.2 billion trade surplus for June 2026. This reflects total exports of K29.6 billion against imports of K25.4 billion. This balance marks a 40% decrease from May's K7.0 billion surplus. The broader quarterly context reveals robust momentum. For the second quarter of 2026, the cumulative trade balance reached K14.8 billion, a marked improvement over the K11.3 billion recorded in the first quarter. By the close of June, the year-to-date trade balance stood at K26.1 billion, illustrating a resilient export sector that stands to gain further from July's reduced transport overheads.
What The Figures Mean for The People Behind Them
Statistics only serve their purpose when the people reading them recognise their own circumstances somewhere inside the numbers, and that is the standard Ms. Mudenda set for this bulletin. Her perspective suggests that a national average is only useful if it can still be traced back down to the district, the household, and the shopping basket it claims to track. Economic policy relies on these granular distinctions to function effectively. A uniform approach to inflation mitigation cannot address a bifurcated market where urban centres absorb rising non-food costs and rural districts adapt to supply chain premiums.
For a household in Chilubi paying K400 for the same bag of mealie meal that costs K199 in Lusaka, the national inflation rate of 6.5% provides a baseline, though local markets require tailored commercial strategies. July's Monthly Bulletin does not set out to resolve that gap. What it does, through 440 tracked items, 116 districts, and ten distinct provincial stories folded into a single national average, shows where that gap sits and how wide it has grown. Mapping these specific local realities provides the commercial sector with the precise coordinates required to navigate the Zambian market, moving beyond headline stability to address the structural opportunities beneath it.